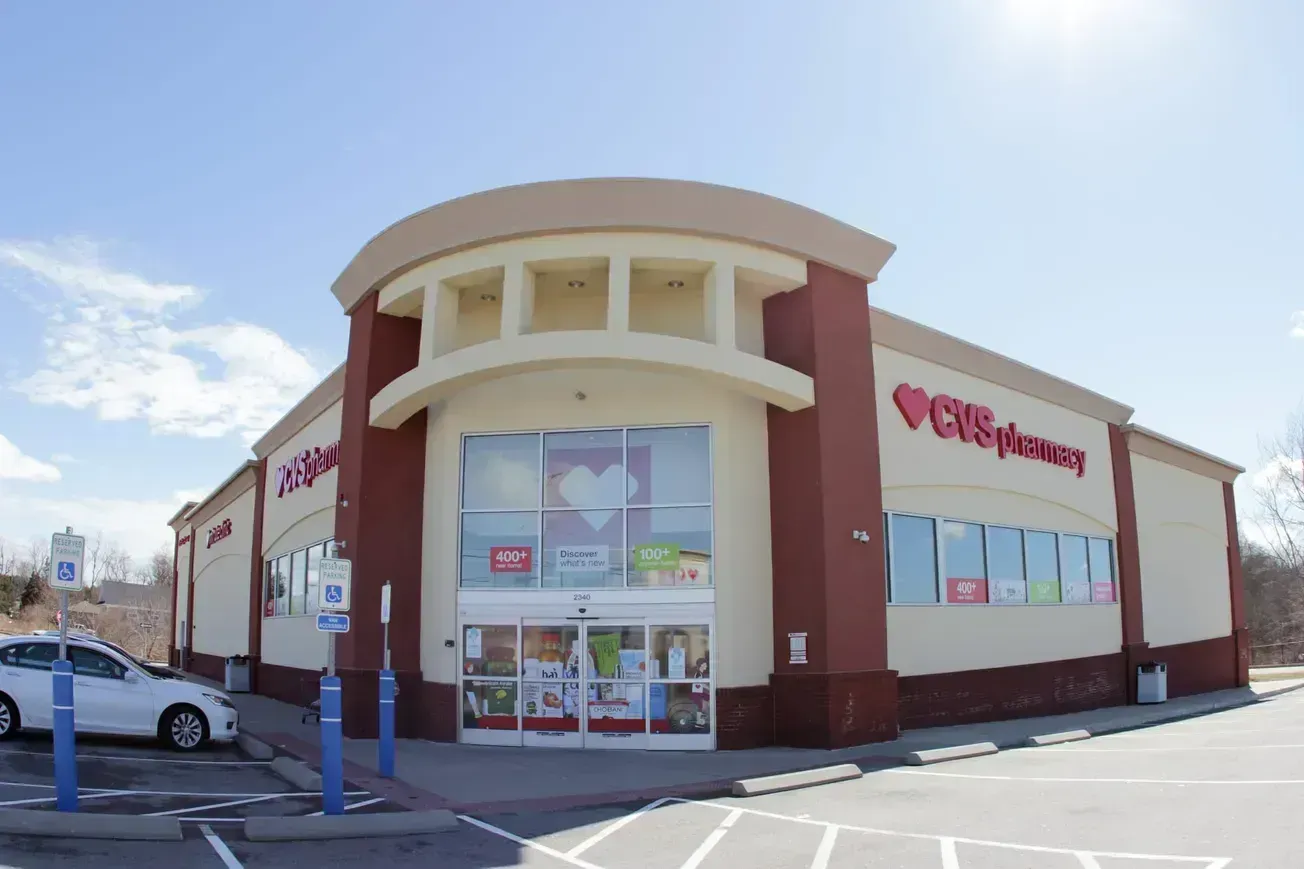
WOONSOCKET, R.I. — CVS Health easily beat third quarter earnings estimates and raised its full-year guidance.
The company posted adjusted earnings per share of $2.09, far exceeding Wall Street's consensus projection of $1.65.
Revenue of $108.4 billion for the three months ended September 30 topped analysts' forecast of $104.75 billion.
The company raised its GAAP diluted EPS guidance for the year to at least $6.98 from a range of $6.84 to $7.04.
It boosted its adjusted full year EPS guidance to at least $8.20 from a range of $7.90 to $8.10
The projection for cash flow from operations was raised to at least $15.5 billion from at least $11.5 billion.
“Our colleagues build trust every day through delivering quality health care rooted in our purpose — to simplify health care one person, one family and one community at a time," said chairman and CEO Dave Joyner. "Through their continued dedication, each of our businesses delivered another quarter of strong results. We continue to advance our strategy by improving the consumer experience, lowering health care costs, and connecting care for the people we serve.”
Third quarter GAAP diluted earnings per share of $1.68 compared to a loss per share of $3.13 in the prior year, reflecting the absence of a $5.7 billion goodwill impairment charge recorded in the 2025 period. Adjusted EPS of $2.09 increased from $1.60 in the prior year, primarily due to improved adjusted operating income in the Health Care Benefits segment, reflecting continued execution of its margin recovery plan.
Total revenues increased 5.4% primarily driven by growth in the Health Services and Health Care Benefits segments.
Operating income of $3.6 billion compared to an operating loss of $3.2 billion in the prior year. The difference was primarily driven by the absence of the $5.7 billion goodwill impairment charge related to the Health Care Delivery reporting unit and an increase in adjusted operating income, which grew 21.2%, primarily driven by increases across all operating segments.
Health Care Benefits segment
• Total revenues increased 2.4% compared to the prior year primarily driven by an increase in the Government business, partially offset by a decline as a result of the company’s exit of the individual exchange business in 2026.
• Adjusted operating income increased significantly compared to the prior year primarily driven by improved underlying performance in the government business.
• The MBR decreased to 91.3% compared to 92.8% in the prior year primarily driven by improved underlying performance in the government business.
• Medical membership as of September 30 of 26.1 million remained consistent compared with June 30.
• Prior years’ health care costs payable estimates developed favorably by $1.3 billion during the nine months ended September 30.
• Days claims payable were 41.9 days as of September 30, an increase of 0.2 days compared to June 30.
Health Services segment
• Total revenues increased 9.5% compared to the prior year primarily driven by pharmacy drug mix and brand inflation, partially offset by continued pharmacy client price improvements.
• Adjusted operating income increased 2.7% compared to the prior year primarily driven by improved purchasing economics and pharmacy drug mix, partially offset by continued pharmacy client price improvements.
• Pharmacy claims processed increased 1.3% on a 30-day equivalent basis compared to the prior year.
Pharmacy & Consumer Wellness segment
• Total revenues decreased 2.0% compared to the prior year primarily driven by regulatory-related price reductions on certain drugs, the impact of recent generic drug introductions and pharmacy reimbursement pressure. These decreases were partially offset by pharmacy drug mix, increased prescription volume, including contributions from the company’s Rite Aid asset acquisitions which were completed during the third quarter of 2025, and brand inflation.
• Adjusted operating income increased 10.6% compared to the prior year primarily driven by core pharmacy strength and contributions from the company’s Rite Aid asset acquisitions. These increases were partially offset by continued business investments and the impact of consumer dynamics.
• Prescriptions filled increased 1.9% on a 30-day equivalent basis compared to the prior year primarily driven by increased utilization and incremental volume resulting from the company’s Rite Aid prescription file acquisitions, partially offset by the absence of long-term care pharmacy prescription volume following the deconsolidation of Omnicare, LLC (“Omnicare”) in September 2025.